Best for an as-is sale without agent commissions: Matallana Capital. Best for comparing direct offers yourself: independently verified cash investors. Best for seller representation: an agent-sourced cash buyer. This 2026 Georgia guide explains which route fits your foreclosure situation and what must be checked before you sign.
- Matallana Capital fits Georgia homeowners seeking an as-is cash sale without agent commissions.
- For a sell house in foreclosure cash buyer search, verify funding, mortgage payoff, and foreclosure timing before signing.
- Compare net proceeds and contract conditions, not just the offer amount.
- A cash offer alone does not stop foreclosure; confirm deadlines with your lender and a Georgia attorney.
Why this matters
A foreclosure deadline changes how you evaluate a buyer. An attractive offer does not help if the buyer cannot fund the purchase, the mortgage payoff is unresolved, or closing cannot occur before the relevant deadline.
Matallana Capital is a fit for Georgia homeowners who want an as-is cash sale without agent commissions. The confirmed offer includes covered closing costs, a seller-chosen closing date, and direct contact with Carlos and a small local team. Your preferred date still needs to work with title clearance, lender requirements, and the foreclosure timeline.
This guide prioritizes homeowners in Gwinnett, Cobb, North Fulton, and DeKalb. It compares selling routes rather than presenting an unsupported ranking of named companies.
What makes the best foreclosure cash buyer?
For a Georgia foreclosure sale in 2026, judge buyers against these criteria before comparing offers:
- Verified funding: Request current proof of funds and confirm who will purchase the property.
- Workable closing date: Match the proposed closing with your lender's information and your attorney's advice about deadlines.
- Clear net proceeds: Compare the amount remaining after mortgage payoff, liens, and seller obligations.
- As-is terms: Check whether the contract requires repairs, cleanup, or later concessions.
- Contract certainty: Read inspection rights, cancellation conditions, and assignment language before accepting.
- Direct accountability: Know who signs, who funds the purchase, and who answers questions through closing.
Do not substitute a promise of speed for these checks. A buyer's preferred schedule is not confirmation that your property can legally and practically close on that date.
Georgia foreclosure cash buyers at a glance
These options serve different needs. The ranking reflects fit and transaction structure, not measured company performance or a guarantee of the highest offer.
| Buyer or route | Best for | Standout feature | Key limitation |
|---|---|---|---|
| Matallana Capital | As-is sellers avoiding agent commissions | Covers closing costs; seller chooses the closing date subject to transaction requirements | A cash offer still needs comparison against your payoff and other selling options |
| Independently verified cash investors | Homeowners managing their own offer comparison | Direct access to competing purchase proposals | You handle buyer verification and contract comparisons |
| Agent-sourced cash buyer | Homeowners seeking seller representation | An agent can coordinate marketing, offers, and negotiation | Agent compensation and marketing steps must be considered |
A traditional listing can also produce financed offers. If you choose that route, tell the agent that you want cash proposals evaluated against the actual foreclosure deadline, not simply a target moving date.
1. Matallana Capital: best for an as-is foreclosure sale
Matallana Capital buys Georgia houses as-is, charges no agent commissions, and covers closing costs. You deal directly with Carlos and a small local team, and you choose a preferred closing date rather than accepting an invented universal closing deadline.
That offer is relevant when repairs or property preparation stand between you and a conventional listing. It also gives you specific terms to compare against other proposals instead of relying on a general promise to make selling easy.
Pros:
- You can sell as-is rather than completing repairs as a condition of the stated offer.
- No agent commissions apply to the direct purchase.
- Covered closing costs simplify the comparison of transaction expenses.
- Direct contact with Carlos and the small local team gives you a clear point of contact.
Cons:
- The convenience of a direct cash sale can involve a trade-off against broader market exposure.
- A preferred closing date does not override title problems, lender requirements, or foreclosure deadlines.
- Covered closing costs do not mean an existing mortgage balance or lien disappears.
Best for: Georgia homeowners with a repair-heavy or unwanted property who want a direct sale without agent commissions.
Before accepting, request the offer and purchase terms in writing. Ask what remains your responsibility, whether the buyer has cancellation rights, and what happens if title work reveals an issue.
Verdict: Consider this route first when as-is terms and a direct point of contact matter most; sign only after checking payoff and timing.
2. Verified cash investors: best for comparing direct offers yourself
An independent cash investor is another direct purchaser you can evaluate without automatically hiring a listing agent. This route suits homeowners who want to gather proposals, ask questions, and manage the comparison themselves.
Do not treat the phrase cash buyer as proof of funding. Establish whether the person contacting you will purchase the home or intends to assign the contract to another buyer.
Pros:
- You can compare written proposals against the same property information.
- You can ask each buyer to specify repair requirements, inspection rights, and closing conditions.
- Direct discussions let you explain occupancy and timing before accepting an offer.
Cons:
- You must check the buyer's identity, funding, and role in the transaction.
- Offers can use different cost allocations and cancellation terms, making headline amounts misleading.
- Contacting additional buyers does not extend a foreclosure deadline.
Best for: Homeowners who can manage buyer screening and want competing direct offers before deciding.
For your 2026 offer comparison, request 2 written offers when the timeline allows. Give both buyers the same description of repairs, occupancy, and known title issues so you are comparing responses to the same situation.
This is a comparison method, not a reason to delay urgent legal advice. If a sale date is approaching, ask your attorney which actions need attention immediately.
Verdict: Consider this route if you can verify buyers and compare contracts without losing necessary time.
3. Agent-sourced cash buyers: best for seller representation
A listing agent can seek cash offers while representing you in the sale. This route is distinct from contacting a purchasing company directly: the agent helps you market and negotiate rather than automatically becoming the buyer.
Ask the agent how the proposed listing approach fits your foreclosure situation. Marketing a home and obtaining a workable contract are separate from completing the sale.
Pros:
- You have a representative to help organize offers and negotiations.
- Marketing can expose the property to buyers beyond those you contact yourself.
- You can ask the agent to compare cash proposals with other available selling routes.
Cons:
- Agent compensation needs to be included in your net-proceeds comparison.
- Showings and marketing introduce tasks that a direct sale can avoid.
- Finding an interested buyer does not guarantee closing before foreclosure.
Best for: Homeowners who want seller representation and have a timeline that supports the proposed marketing plan.
Agree on the property's presentation before listing. If you want an as-is sale, make that instruction clear rather than assuming repairs or cleanout are required.
Request a written estimate of your likely seller proceeds for each serious proposal. An offer with more market exposure is not automatically the better outcome after costs and conditions.
Verdict: Consider this route when representation and broader exposure matter more than minimizing selling steps.
How to compare a cash offer before signing
Use the same review process for every buyer in 2026. Keep the lender's timeline separate from the buyer's promises until the professionals handling the transaction confirm how they fit together.
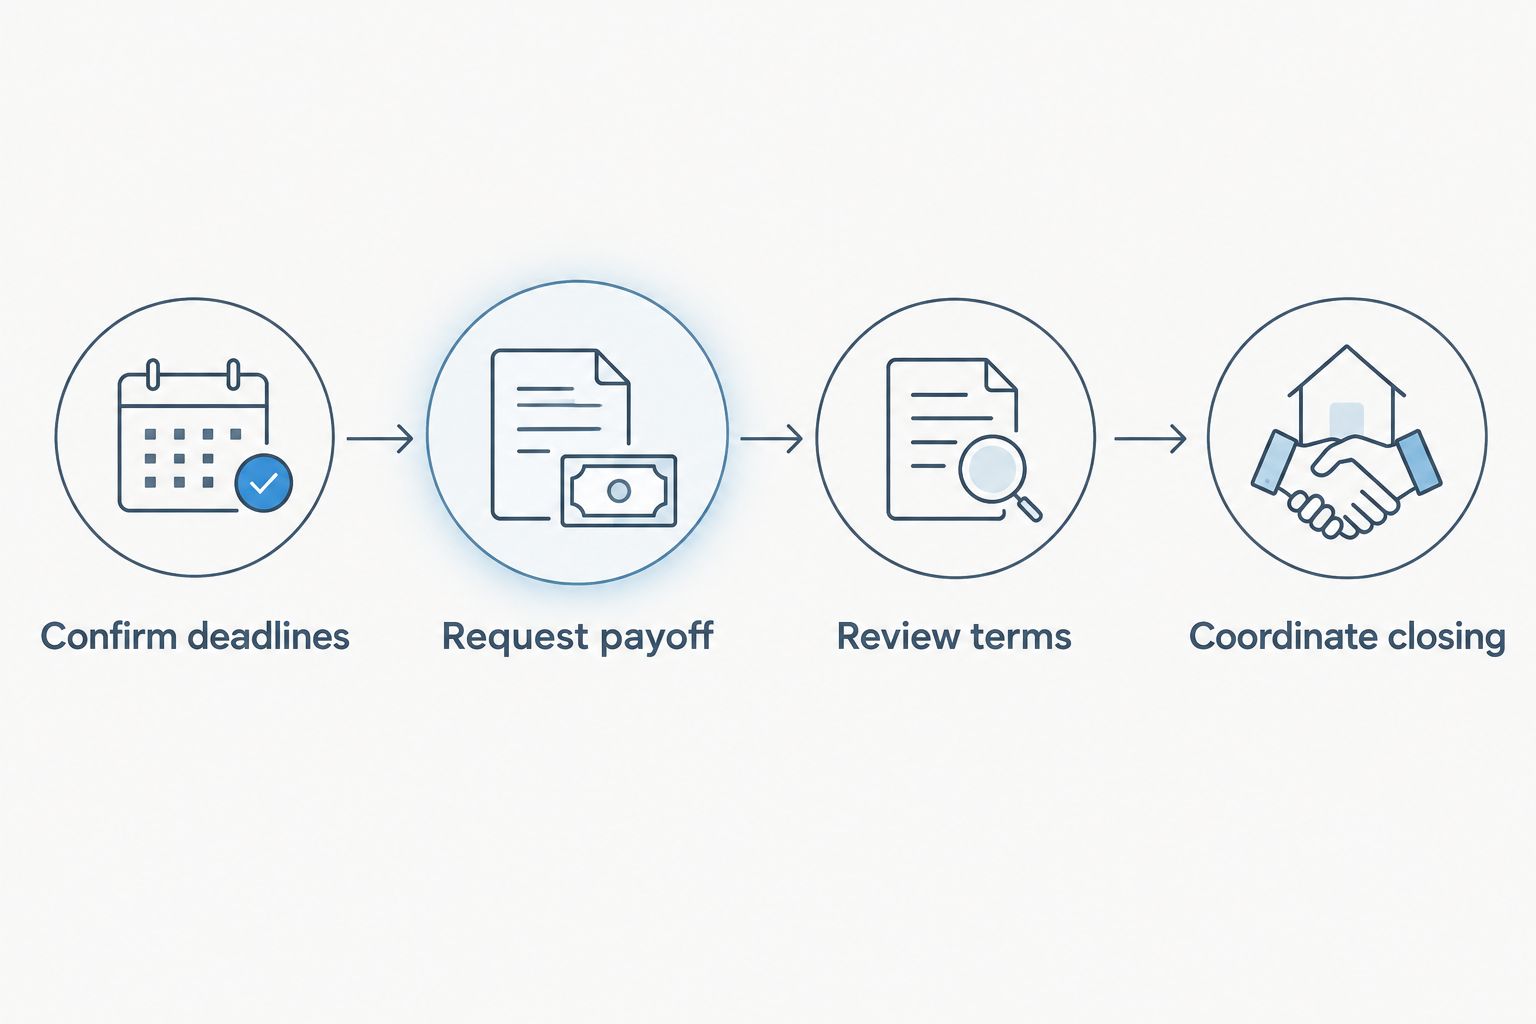
Confirm deadlines
Locate your foreclosure notices and ask the lender or loan servicer for the current status. Have a Georgia foreclosure attorney explain the relevant deadlines and available options; a purchase offer is not a legal pause button.
Request payoff
Request a current mortgage payoff statement through the appropriate process. A payoff amount is not necessarily the same as the balance displayed on your regular statement.
Identify other known liens or ownership issues for the closing attorney. Do not assume the buyer's offer leaves you with proceeds until those obligations have been accounted for.
Review terms
Check 3 figures side by side: the purchase offer, total payoff obligations, and estimated seller proceeds. Then review inspection rights, cancellation conditions, assignment rights, possession terms, and responsibility for expenses.
An offer above the mortgage balance does not automatically establish your final proceeds. Ask for a written settlement estimate rather than doing the comparison from the headline offer alone.
Coordinate closing
Ask the buyer and closing attorney what remains outstanding and who must supply it. Confirm the planned closing against the foreclosure timeline with your lender and legal adviser.
Do not stop responding to lender notices because a buyer says the transaction is progressing. Keep copies of documents and written communications together.
Match the sale plan to the property's situation
A 2026 foreclosure sale needs more than a buyer who accepts the property's appearance. Ownership, occupancy, and lender requirements also shape what must happen before closing.
- Homes needing repairs: Describe known issues accurately. Ask whether the written offer includes repairs, cleanup, or inspection-related renegotiation.
- Inherited homes: Confirm who has authority to sign. A cash buyer does not replace the legal work needed to establish ownership or authority to sell.
- Tenant-occupied homes: Share the lease and occupancy details with your attorney and buyer. Do not promise vacant possession without understanding your obligations.
- Urgent sales: Provide the actual notice and deadline information rather than saying only that you need to sell quickly.
You do not need to minimize the property's problems to request an offer. Accurate information helps identify transaction obstacles before you rely on a proposed date.
How these options were ranked
The ranking prioritizes the confirmed offer terms, your role in managing the transaction, and whether you want seller representation. Funding, timing, net proceeds, contract conditions, and accountability remain the deciding criteria for every route.
No buyer earns a recommendation solely by using the words cash or fast. The right choice is the one whose written terms and closing requirements fit your situation.
Which foreclosure cash buyer should you choose?
Start with Matallana Capital if you want an as-is cash offer without agent commissions and direct contact with Carlos and the local team. Compare the written proposal with your payoff obligations and another selling route when time permits.
Choose independent investor comparisons if you want to manage the process yourself. Choose an agent-sourced cash buyer if seller representation and broader exposure are your priorities.
For any route, legal deadline questions come first. This guide provides general information, not advice about your specific foreclosure.
Request an as-is cash offer
Explain the property's condition, occupancy, and foreclosure timing to Carlos and the local team.
FAQ
Can I sell my Georgia house while it is in foreclosure?
A sale before foreclosure can be possible, but ownership, payoff requirements, and deadlines determine whether it can close. Ask your loan servicer and a Georgia foreclosure attorney to confirm your situation before relying on a buyer's schedule.
Does accepting a cash offer stop foreclosure?
No. Accepting a cash offer does not by itself stop foreclosure. Confirm any change to the foreclosure process with your lender and legal adviser rather than relying on the purchase contract alone.
What's the best cash buyer for a house needing repairs?
An as-is buyer with verified funding and workable written terms is the relevant fit for a house needing repairs. Compare repair requirements, inspection rights, cancellation conditions, and estimated proceeds before choosing.
Can I choose the closing date for a cash sale?
You can request a closing date, but the transaction must still satisfy title, lender, and legal requirements. A preferred date is not an unconditional guarantee that closing can occur then.
Will a cash buyer pay off everything I owe?
Do not assume an offer covers every obligation. Compare the purchase amount with the current mortgage payoff, other liens, and transaction obligations; if the proceeds are insufficient, discuss the available options with your lender and attorney.
Can I sell a tenant-occupied house facing foreclosure?
A tenant-occupied sale requires attention to the lease and applicable legal obligations. Give the buyer accurate occupancy information and get legal advice before promising that tenants will leave.
Is a cash buyer better than listing with an agent?
A direct cash buyer fits sellers prioritizing an as-is transaction and fewer marketing steps; an agent fits sellers seeking representation and broader exposure. Compare net proceeds, contract conditions, and the foreclosure timeline rather than assuming either route always wins.
One last thing
The purchase offer is not the number you take home. Before signing, ask for a 1-page summary showing the offer, payoff obligations, seller expenses, estimated proceeds, and unresolved closing conditions.
That summary makes the decision concrete. If any line is unclear, get an explanation before treating the sale as your foreclosure solution.